
Market opportunities and risks that could shape the months ahead
Review the latest Weekly Headings by CIO Larry Adam.
- Despite economic crosscurrents, the US economy remains on solid footing
- Today’s fixed income market offers advantages that didn’t exist five years ago
- US equities continue to deliver strong earnings at this stage of the bull market
This year has marked another remarkable chapter for the global economy and financial markets. Investors have navigated no shortage of challenges, from geopolitical conflicts and trade tensions to elevated energy prices and shifting interest rate expectations. Yet despite these headwinds, the economy continues to expand, corporate earnings remain resilient and markets have steadily climbed the proverbial wall of worry.
Investors have had to navigate uncertainty, adapt to changing conditions, and stay disciplined in the face of unexpected obstacles. Here, we chart a course through the economic and market landscape and examine the opportunities and risks that could shape the months ahead.
The US economy overcomes waves
Despite economic crosscurrents, the US economy remains on solid footing. The consumer, who accounts for roughly two-thirds of GDP, continues to demonstrate resilience, with real-time activity metrics still pointing to healthy spending and rising household wealth providing ongoing support. Meanwhile, investment tied to the AI buildout is becoming an increasingly important driver of economic growth. The benefits extend well beyond AI itself, supporting demand for data centers, power generation, electrical equipment, construction and infrastructure required to connect these systems. Together, these forces continue to support the economic expansion. While the cycle is maturing and is now in its sixth year, we see few signs that the underlying currents are turning meaningfully less supportive and expect 2.3% GDP in 2026 and 2.2% in 2027.
Monetary policy navigating a difficult stretch
The Federal Reserve (Fed) must steer between competing risks while keeping the economy on course, balancing between restoring price stability and preserving economic momentum. With the labor market remaining healthy, the Fed’s focus has shifted to inflation. While a combination of shocks – tariffs, energy and continued investment demand tied to the AI buildout – has kept inflation elevated, these pressures should begin to ease. We anticipate the Fed will deliver one additional rate increase before year-end (likely December) as part of a mid-cycle adjustment to bring inflation back to target in a timely manner. Further progress on inflation could open the door to lower rates toward the end of next year. Until then, the Fed is likely to maintain a cautious stance and keep policy restrictive unless labor market conditions materially weaken.
Higher yields help investors navigate the journey
The sharp rise in yields from the post-pandemic lows has improved the resilience of fixed income within diversified portfolios. While higher yields cannot eliminate every storm, they can help keep portfolios balanced when turbulence appears, as they have throughout history. Today’s fixed income market offers advantages that didn’t exist five years ago: attractive income; an income buffer that can help absorb losses; and compelling total return potential if growth softens. More importantly, investors can earn generous yields without taking excessive credit risk. While yields remain elevated, cooling inflation and easing geopolitical tensions should help bring the 10-year Treasury yield back toward our 4.5%-4.75% target range over the next 12 months. While the US national debt remains a long-term concern, we do not view this as a near-term threat as demand for US Treasuries remains healthy.
US equities continue to lead
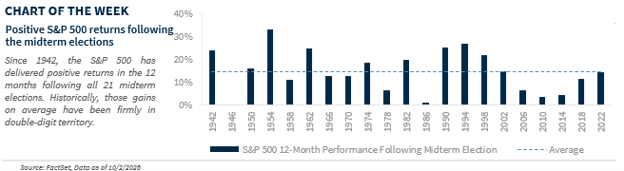
The US equity bull market will shortly enter its fifth year with remarkable resilience. In fact, corporate America has delivered far stronger earnings than we typically see at this stage of the bull market – and that strength is expected to continue in the quarters ahead. History provides another tailwind, as both the fifth year of a bull market and 12 months following the midterm elections have historically been supportive for returns. While concerns surrounding Fed rate hikes, higher long-term interest rates and geopolitical risks bear watching, the earnings outlook should help offset any near-term obstacles. As a result, our 12-month S&P 500 target is 8,450 (~11% upside from current levels). Technology remains the market’s Achilles: powerful, dominant and central to market leadership. Investors continue to search for an Achilles heel, citing valuation concerns, market concentration, and reliance on a handful of tech leaders. Yet robust earnings growth and more reasonable valuations suggest the sector’s strengths continue to outweigh these risks.
Different shores, different opportunities globally
While the US remains our preferred destination, supported by stronger economic growth, superior earnings momentum and leadership in artificial intelligence, some opportunities abroad remain compelling. We continue to favor emerging markets Asia, one of the clearest beneficiaries of the global AI investment cycle. Japan also stands out among developed markets, supported by solid earnings growth, a return to modest inflation and meaningful technology exposure. Meanwhile, Latin American equities could face headwinds from lower oil prices next year.
All expressions of opinion reflect the judgment of the author(s) and the Investment Strategy Committee and are subject to change. This information should not be construed as a recommendation. The foregoing content is subject to change at any time without notice. Content provided herein is for informational purposes only. There is no guarantee that these statements, opinions or forecasts provided herein will prove to be correct. Past performance is not a guarantee of future results. Indices and peer groups are not available for direct investment. Any investor who attempts to mimic the performance of an index or peer group would incur fees and expenses that would reduce returns. No investment strategy can guarantee success.
Economic and market conditions are subject to change. Investing involves risks including the possible loss of capital.
The information has been obtained from sources considered to be reliable, but we do not guarantee that the foregoing material is accurate or complete. Diversification and asset allocation do not ensure a profit or protect against a loss.
The S&P 500 Total Return Index: The index is widely regarded as the best single gauge of large-cap U.S. equities. There is over USD 7.8 trillion benchmarked to the index, with index assets comprising approximately USD 2.2 trillion of this total. The index includes 500 leading companies and captures approximately 80% coverage of available market capitalization.
Sector investments are companies focused on a specific economic sector and are presented here for illustrative purposes only. Sectors, including technology, are subject to varying levels of competition, economic sensitivity, and political and regulatory risks. Investing in any individual sector involves limited diversification.
